Photo credit: New York Stock Exchange/Youtube
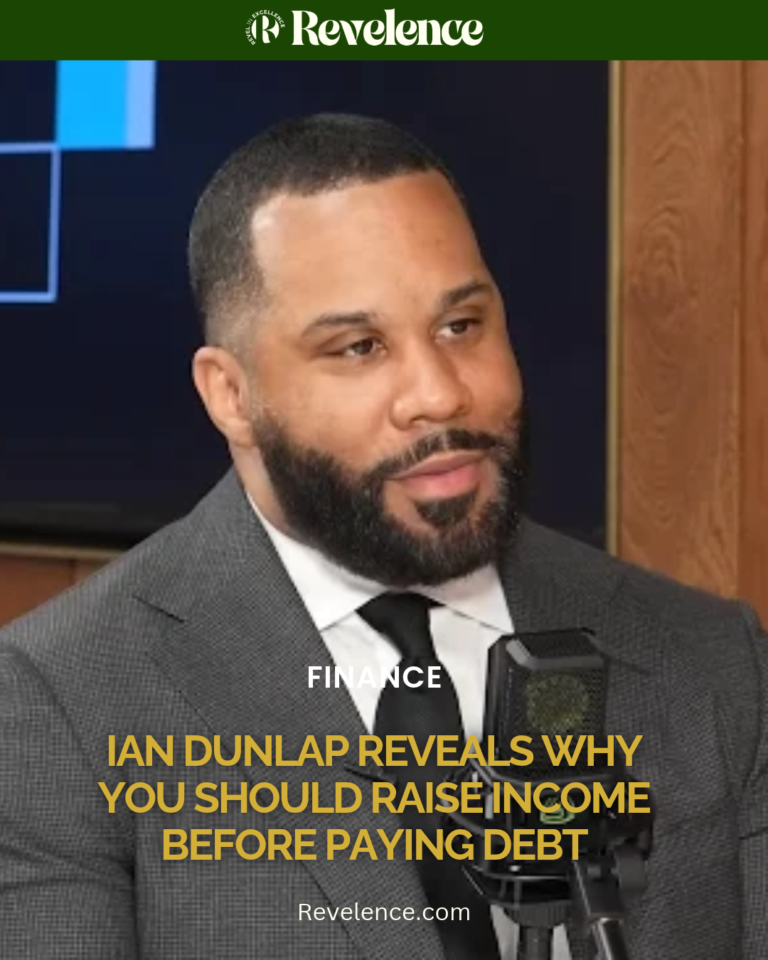
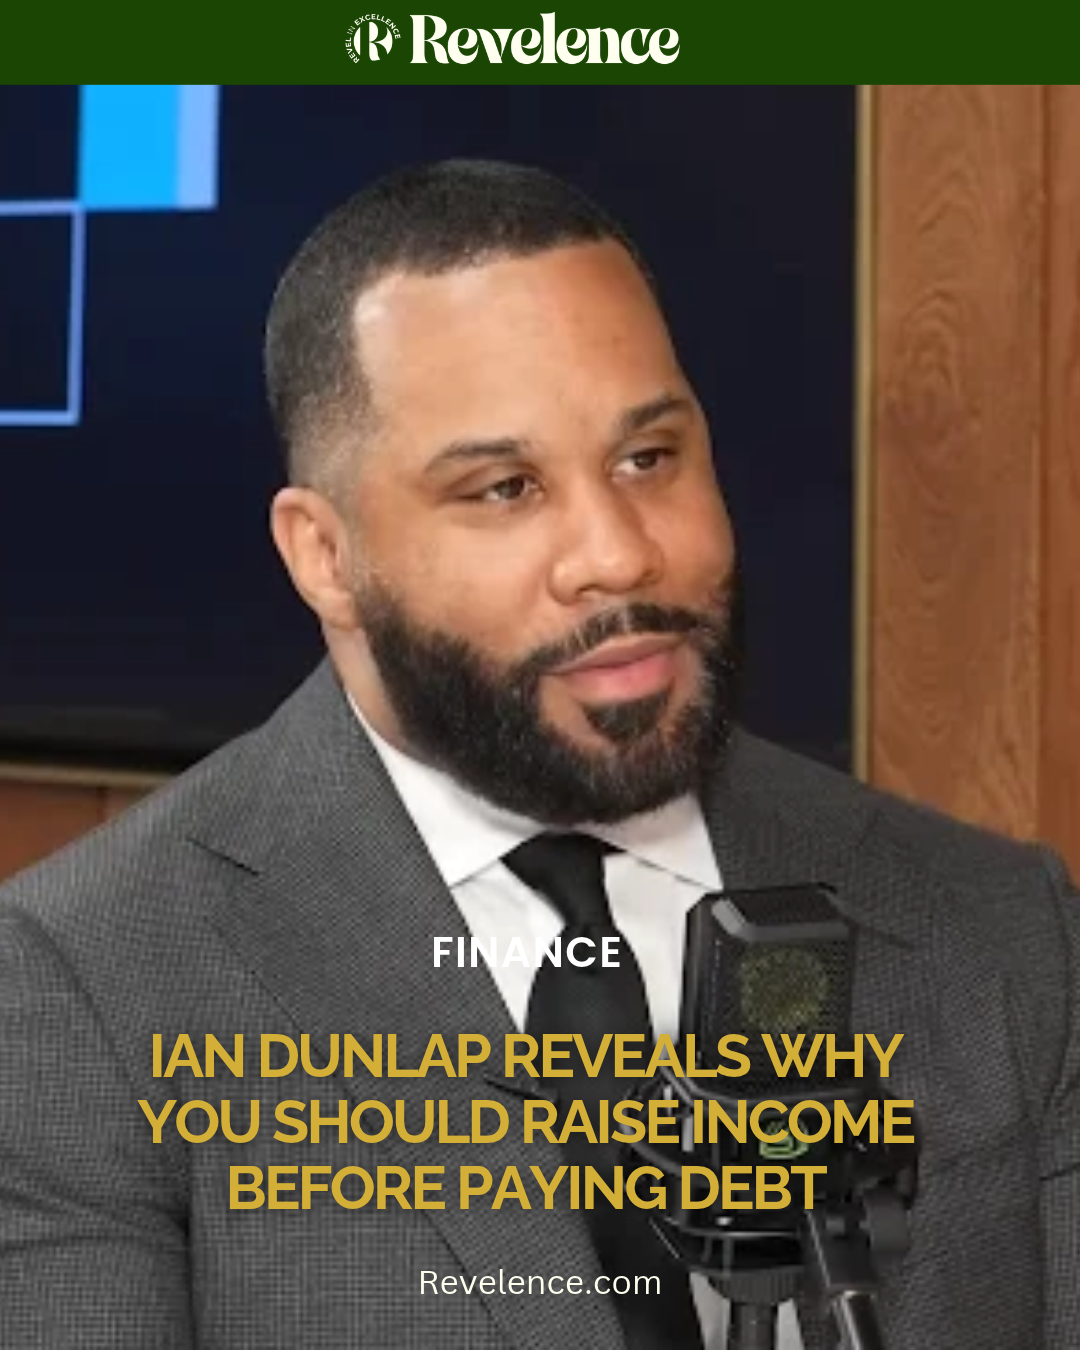
Ian Dunlap is challenging conventional money advice with a wealth-building strategy that puts increasing income ahead of paying off debt.
The investor, widely known as the Master Investor and associated with Market Mondays, argues that people with limited money should focus on improving their cash flow before deciding how much to invest or use to clear outstanding balances.
His position challenges the familiar advice to become debt-free before investing. Instead, Dunlap believes people can create more financial flexibility by earning more, saving part of every income increase and investing before tackling debt.
The discussion comes as Americans continue to carry trillions of dollars in household debt, raising questions about how people can balance financial security with long-term wealth building.
Ian Dunlap Wants People to Increase Income First
During the discussion, Dunlap was asked what he would recommend to people who have limited money and must choose between investing, paying off debt or increasing their income.
His answer placed income growth first.
Dunlap explained that earning more money can improve cash flow and create opportunities to save and invest. He also recommended setting aside half of any income increase rather than spending the entire amount.
That approach could help people build savings while improving their financial position. For example, someone who receives a raise could direct half of the additional income into savings and use the rest to meet other financial goals.
Dunlap then placed investing second in his proposed strategy. He argued that people who follow his guidance should consider investing in the market before making debt repayment their final priority.
However, he acknowledged that people without the same guidance might prefer to pay down debt first. His comments highlight the different ways people approach money management and the trade-offs involved in each decision.
Why the Debt Debate Matters Now
Dunlap’s comments come amid continued pressure on American household finances.
The Federal Reserve Bank of New York reported that U.S. credit card balances reached $1.263 trillion at the end of June 2026. Balances rose by $21 billion during the second quarter, while total household debt stood at $18.771 trillion. The report also found that 4.7% of outstanding household debt was in some stage of delinquency. <Cite refs={[“turn845366search0”]} />
These figures help explain why debt repayment remains a major concern for consumers. At the same time, people looking to build wealth may want to increase their earnings and establish savings rather than direct every available dollar toward existing balances.
Dunlap’s argument shifts attention toward earning power. Instead of focusing exclusively on how much money someone owes, his approach asks whether that person has enough income to cover expenses, build reserves and invest for the future.
Is Investing Before Paying Off Debt the Right Move?
Dunlap’s strategy offers a different perspective, but it does not work equally well for everyone.
High-interest credit card debt can become more expensive over time. Paying it down reduces interest costs, while investments carry the risk of losing money. Market returns are never guaranteed, and an investor may need to sell assets at a loss to cover an unexpected expense.
For this reason, people should consider their interest rates, minimum payments, emergency savings and income stability before deciding how to divide their money.
Someone with expensive credit card debt and little savings may need to prioritize financial stability. Meanwhile, a person with manageable, low-interest debt and reliable income may have more room to invest while continuing regular repayments.
Dunlap’s approach should therefore be understood as his personal wealth-building philosophy, not a universal financial rule.
Building Wealth Beyond Debt Repayment
Dunlap’s message encourages people to think about their financial future beyond their current balances. Increasing income can create more room for saving, investing and paying down debt without leaving a household unprepared for unexpected expenses.
Still, earning more money does not automatically guarantee financial progress. Spending habits, interest costs, savings and investment decisions all influence the outcome.
Ultimately, the debate raises an important question for people trying to build wealth: Should paying off debt always come before investing?
Dunlap’s answer challenges that assumption. His strategy starts with earning more, saving a portion of every increase and considering investments before making debt repayment the final priority.
For consumers weighing those options, the best decision depends on their individual financial circumstances, the cost of their debt and their ability to manage investment risk.
Source: Ian Dunlap Podcast
About the Author