Photo by Kampus Production
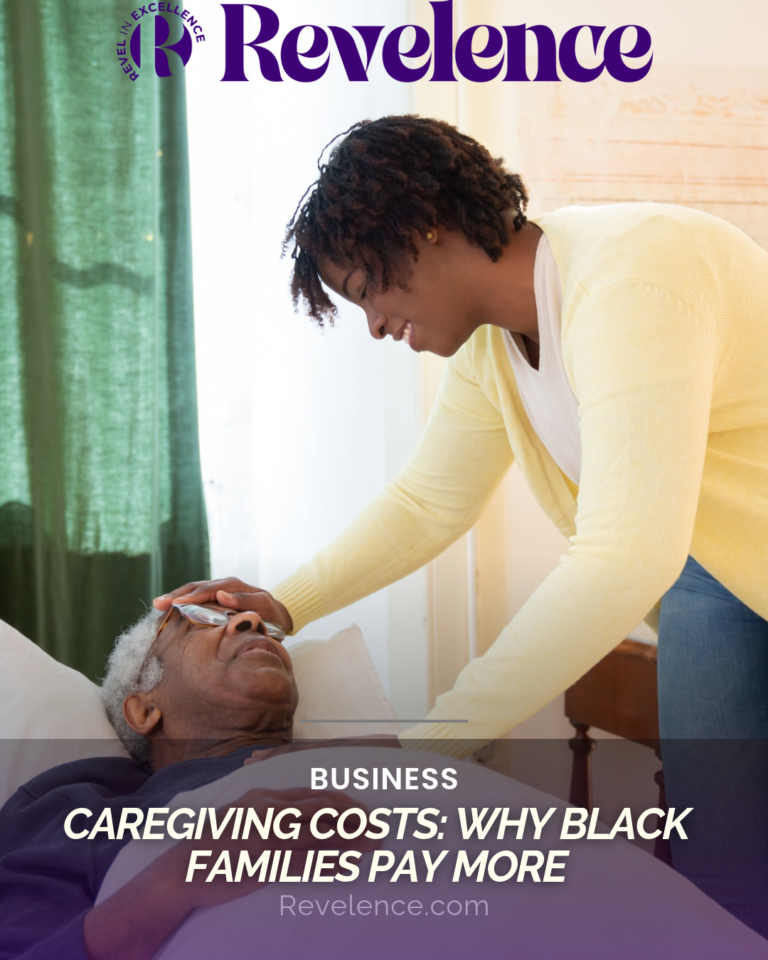
Caring for a loved one is an act of commitment. However, that commitment can come with expenses families rarely discuss until the bills begin to accumulate.
Transportation, groceries, medical supplies and home assistance can quickly affect a household budget. Caregivers may also lose income when they reduce working hours, turn down opportunities or leave their jobs to provide support.
New research from AARP highlights the scale of this financial pressure. Its 2026 research estimates that working caregivers could lose an average of $120,500 in lifetime earnings and retirement-related income.
For Black families, the burden deserves particular attention. A separate AARP study found that Black caregivers spend a larger share of household income on caregiving than other racial groups surveyed.
Making these costs visible can help families have more informed conversations about money, responsibilities and long-term financial security.
The cost of caregiving goes beyond medical bills
Families often think about caregiving expenses in terms of prescriptions, doctor visits and insurance payments. However, the financial picture is much broader.
A caregiver may pay for groceries, household supplies, transportation, home modifications and personal care assistance. Some also cover utility bills or contribute toward rent and other living expenses.
AARP’s October 2026 Caregiving Out-of-Pocket Costs Study found that caregivers spend an average of $11,508 annually on caregiving. That equals approximately $959 each month.
Housing and household expenses account for 42% of reported spending. Medical expenses account for another 29%.
These figures show why families should record everyday purchases alongside major medical bills. Small expenses can become a significant financial commitment over time.
Black caregivers face a heavier income burden
The AARP study found that Black caregivers spend an average of $13,565 annually on caregiving. Those expenses represent 52% of their household income.
By comparison, White caregivers spend an average of $9,806, representing 24% of household income.
This difference deserves attention because the percentage of income spent can affect a family’s ability to save, pay bills and prepare for emergencies.
The findings do not provide a separate financial estimate for Black women. However, they highlight the economic pressure facing Black households and the importance of including caregiving expenses in family financial discussions.
For Black women balancing work, family responsibilities and caregiving, a clear record of contributions can also make it easier to discuss how responsibilities should be shared.
Missed work can create long-term financial losses
Caregiving can affect a person’s career long after an appointment or medical emergency has passed.
Some employees arrive late, leave early or use vacation time to help relatives. Others reduce their hours, turn down promotions or leave employment altogether.
AARP’s November 4 report estimates that working caregivers born between 1981 and 1985 could lose an average of $120,500 in lifetime income. The estimate includes reduced earnings, workplace retirement income and future Social Security benefits.
The report also estimates that caregivers who miss the equivalent of more than two and a half years of full-time work could lose an average of $446,500 over their lifetimes.
These estimates make an important point. Families should consider the financial impact of unpaid care on the person providing it, not only the expenses of the person receiving care.
Create a household caregiving expense record
A shared record can help relatives understand what caregiving actually costs.
Families can start with a simple spreadsheet or budgeting document. Record the date, expense, amount, person who paid and whether anyone reimbursed the cost.
Include categories such as:
- Medical appointments, prescriptions and supplies.
- Groceries, meals and household essentials.
- Transportation, parking and fuel.
- Home modifications and personal care services.
- Childcare or additional support needed while someone provides care.
- Lost wages, reduced work hours and unpaid leave.
Keep receipts and separate caregiving expenses from personal purchases. This makes it easier to review spending and prepare for conversations with a financial professional.
Discuss how the family will share the financial responsibility
One relative should not automatically become responsible for every bill simply because they provide the most hands-on care.
Families can arrange regular conversations about expenses and responsibilities. They should identify who can contribute money, who can provide transportation and who can take on household tasks.
A written agreement can help prevent misunderstandings. It should explain how the family will record contributions, handle reimbursements and review changing needs.
The person receiving care should also participate in financial decisions whenever possible. Families should respect their preferences and avoid sharing financial information beyond those who need it.
Ask a qualified financial professional the right questions
A financial professional can help families understand how caregiving affects their budgets, savings and retirement plans.
Before an appointment, gather recent bills, income information, insurance details and a record of caregiving contributions.
Ask questions such as:
- How can we budget for recurring and unexpected care expenses?
- How might reduced working hours affect retirement savings?
- Are there employer benefits or leave options we should review?
- Could any caregiving expenses qualify for tax deductions or credits?
- How should relatives document shared payments and reimbursements?
- What legal documents should we discuss with an attorney?
Choose a professional with relevant experience in retirement planning, eldercare or family financial planning. Check credentials and understand fees before agreeing to services.
A financial professional can explain options, but tax and legal questions may require a qualified tax adviser or attorney.
Protect the caregiver’s financial future, too
Caregiving plans should include the person providing support.
Families should discuss emergency savings, retirement contributions, insurance and the possibility of paid assistance or respite care. They should also review workplace leave policies before assuming that time away from work will be paid.
In the United States, eligible employees may qualify for unpaid, job-protected leave under the Family and Medical Leave Act when caring for a spouse, child or parent with a serious health condition.
The U.S. Department of Labor provides guidance on eligibility and available protections. However, eligibility requirements apply, and the law does not guarantee paid leave.
Caregiving should not require one family member to quietly sacrifice their financial future. Open conversations, accurate records and professional guidance can help households make more informed decisions.
The first step is simple: put the numbers on paper, bring the family into the conversation and make sure the caregiver’s financial well-being is part of the plan.
sources: AARP
About the Author